


Why use a physical book?
Be more likely to achieve your financial goals
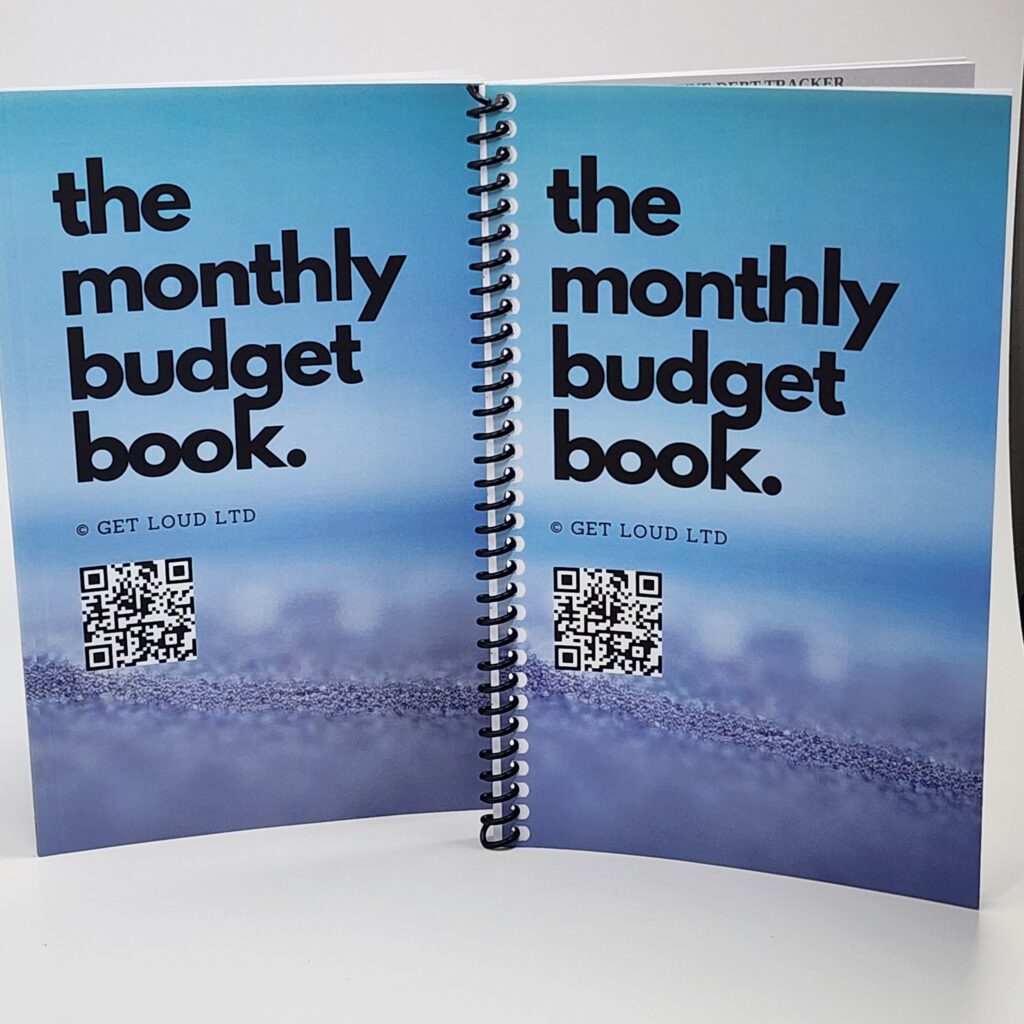
Physical monthly budget books and debt-focused planners are actively sought by people who want tangible progress toward becoming (and staying) debt-free.
Average credit card debt
$5,525


61%
of Americans can’t cover $1,000 emergency expense
Budgeting and success
a written financial plan and a set goal will lead to success

CONTROL AND AWARENESS
Increased awareness helps you make informed financial decisions.

FINANCIAL STABILITY
Avoid living paycheck to paycheck, reduce debt, and build savings for future needs.

GOAL SETTING
A budget helps you allocate resources toward specific objectives.
What’s inside:
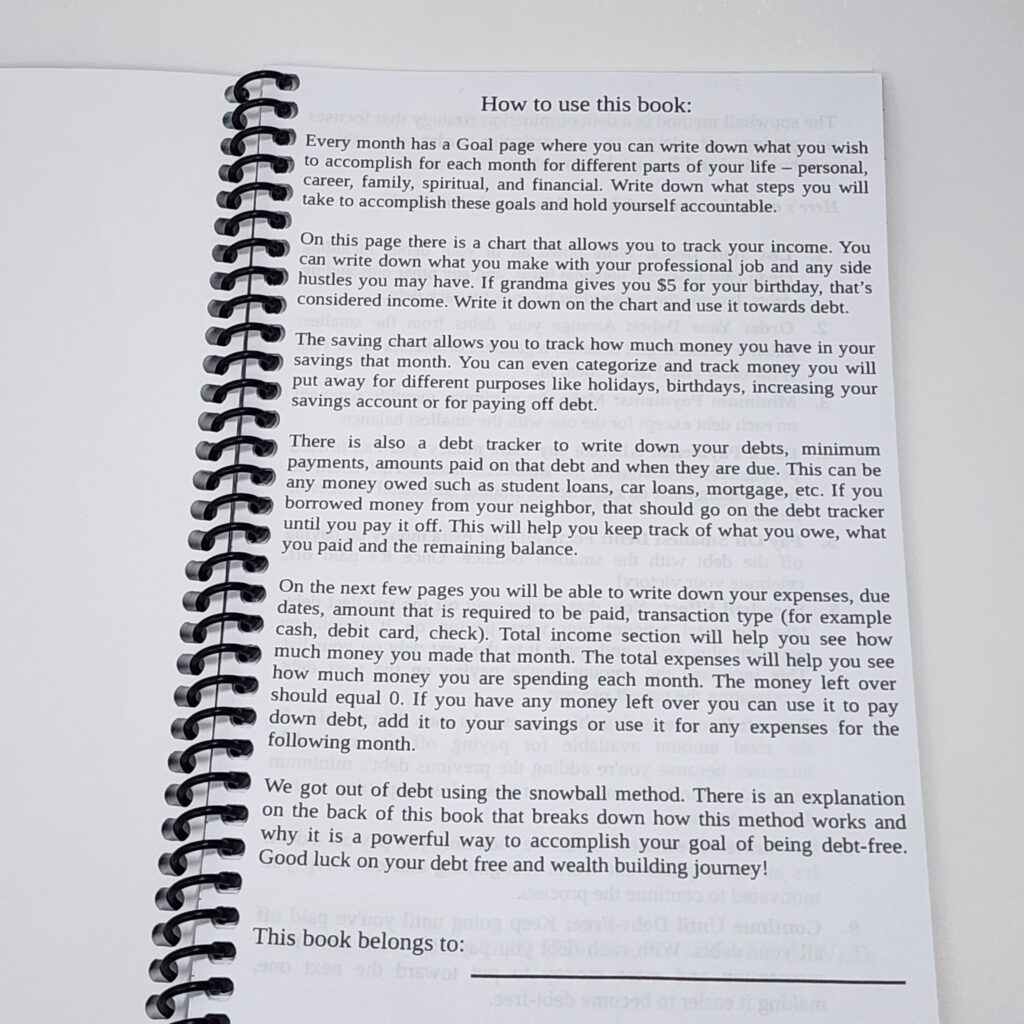
HOW TO USE THE BOOK

Set Monthly Goals
Every month has a Goal page where you can write down what you wish to accomplish for each month for different parts of your life – personal, career, family, spiritual, and financial. Write down what steps you will take to accomplish these goal and hold your self accountable.
On this page there is a chart that allows you to track your income. You can write down what you make with your professional job and any side hustles you may have. If grandma gives you $5 for your birthday, that’s considered income.
The saving chart allows you to track how much money you have in your savings that month or you can even categorize and track money you will put away for different purposes like holidays, birthdays or even to increase your savings account.
Debt Tracker
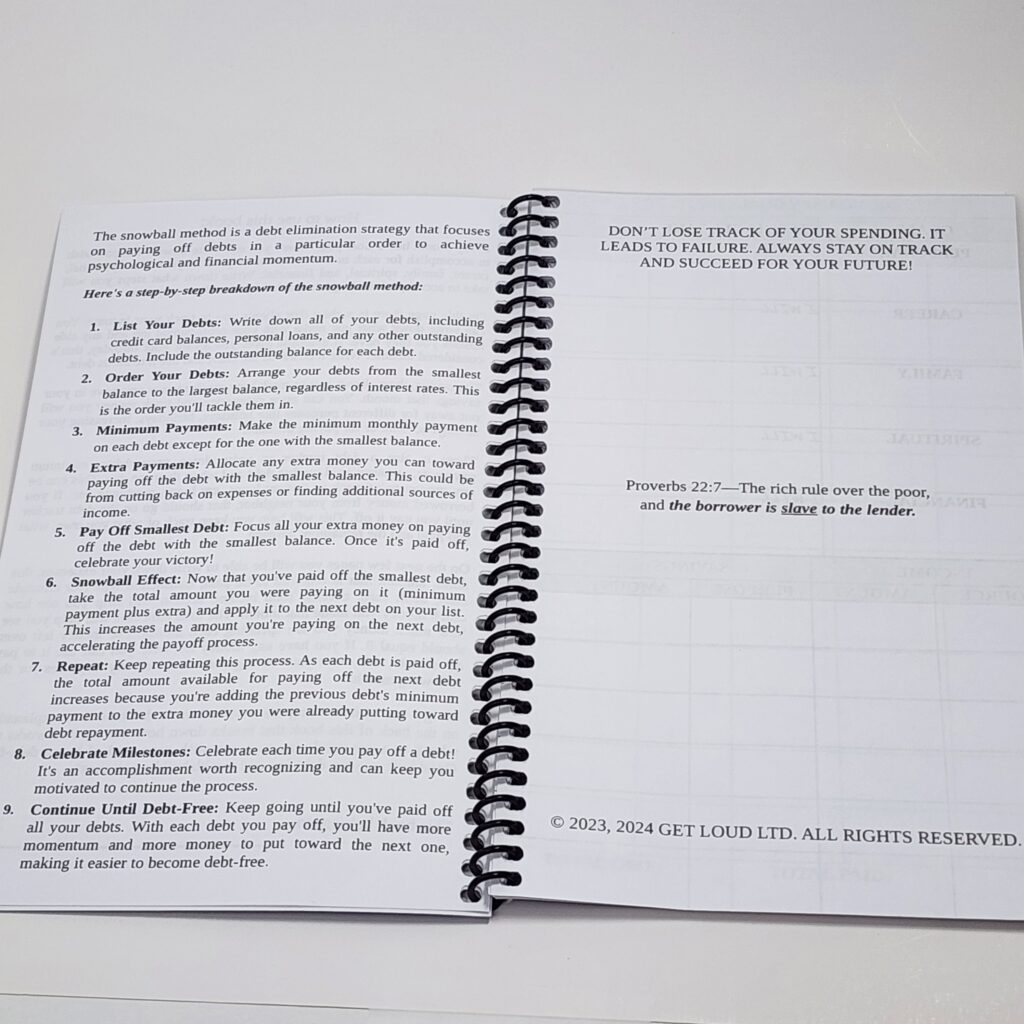
There is also a debt tracker to write down your debt, minimum payments, amounts paid on that debt and when they are due. This can be any money owed such as students loans, car loans, mortgage, etc. If you borrowed money from your neighbor, that should go on the debt tracker until you pay it off. This will help you keep track of what you owe, what you paid and balance remaining.


Expenses
On the next few pages you will be able to write down your expenses, due dates, amount that is required to be paid, transaction type (for example cash, debit card, check).
$0 Budgeting
Total income section will help you see how much money you made that month. The total expenses will help you see how much money you are spending each month. The money left over should be 0, but if you have any money left over you can add it to your savings or use it for any expenses for the following month.

#Facts
- Ramsey Solutions – Redefining Normal: A Ramsey Plan Comparison Study
ramseysolutions.com/budgeting/ramsey-plan-comparison-study
(Compares outcomes of people following the Baby Steps / written budgeting approach vs. the general population on debt, bill-paying, and financial confidence.) - Financial Consumer Agency of Canada (FCAC) – Budgeting over time and why it matters
canada.ca/en/financial-consumer-agency/programs/research/budgeting-time.html
(Longitudinal research linking consistent budgeting to lower credit card debt, better debt management confidence, and improved financial outcomes.) - CNBC – Why this financial coach tells clients to budget with pen and paper
cnbc.com/make-it/2023/10/30/why-this-financial-coach-tells-clients-to-budget-with-pen-and-paper.html
(Discusses the behavioral advantages of handwritten/physical budgeting for awareness, retention, and sticking with the plan.) - The Philadelphia Inquirer – Budgeting by hand is better than apps such as Mint, experts say
inquirer.com/business/mint-budgeting-app-shutting-down-tips-20231112.html
(Covers expert views and survey data on higher long-term adherence with manual methods vs. apps.) - Due.com – The Zero-Based Budget That Helped Me Pay Off $87,000 in Debt (cites Ramsey data)
due.com/zero-based-budget-helped-me-pay-off-87000-in-debt-in-26-months
(Directly references the Ramsey Solutions claim that people using a monthly written budget pay off 19% more debt per year, and zero-based budgeters 23% more.)
Testimonials
What our customers say
Stay Motivated and Stick to Your Budget Goals
Explore the impact of budgeting on debt reduction and financial freedom.